
You’re easing out of a crowded market lane, the rider ahead brakes hard, and your foot peg scrapes the side of his Activa. He isn’t happy. Somewhere at the back of your mind sits the thought that you skipped comprehensive cover this year, so the whole thing is on you.
That’s the part most riders get wrong. This article covers what your policy actually pays for here, what it leaves you to handle, and what to do in the first hour after it happens.
Does Your Third Party Policy Cover the Other Person’s Bike?
Yes. Damage you cause to someone else’s vehicle is exactly what third party liability was built to pay for. This mandatory cover on your bike protects other people from you, not your bike from the road.
Think of it as two separate jobs. Third party liability handles the loss you cause to somebody else. Own damage cover, half bundled into a comprehensive policy, handles the repair bill on your own machine. Skipping comprehensive removes the second job and leaves the first one intact, which is why third party insurance for bike riders is compulsory under the Motor Vehicles Act.
What Does a Third Party Policy Actually Pay For?
It pays the people you harm, not you. Broadly, a third party policy responds to three things:
- Repair or replacement of the other rider’s bike, or any other property you damage, up to the property damage limit written into your schedule
- Compensation if you injure or kill another person, with the amount decided by the Motor Accident Claims Tribunal, the body that hears road accident compensation cases
- Defence costs your insurer agrees to, if the matter reaches a tribunal or court
The property damage side carries a cap, and the figure printed on your own policy schedule is the one that applies to you. Injury claims work differently, because a tribunal sets the award rather than your insurer. Terms and conditions apply. Please refer to the policy wording for full details before purchase.
So, Who Picks Up the Bill for Your Own Bike?
You pay for that yourself. A third party policy has no own damage component, so your fork, fairing and headlamp are your bill.
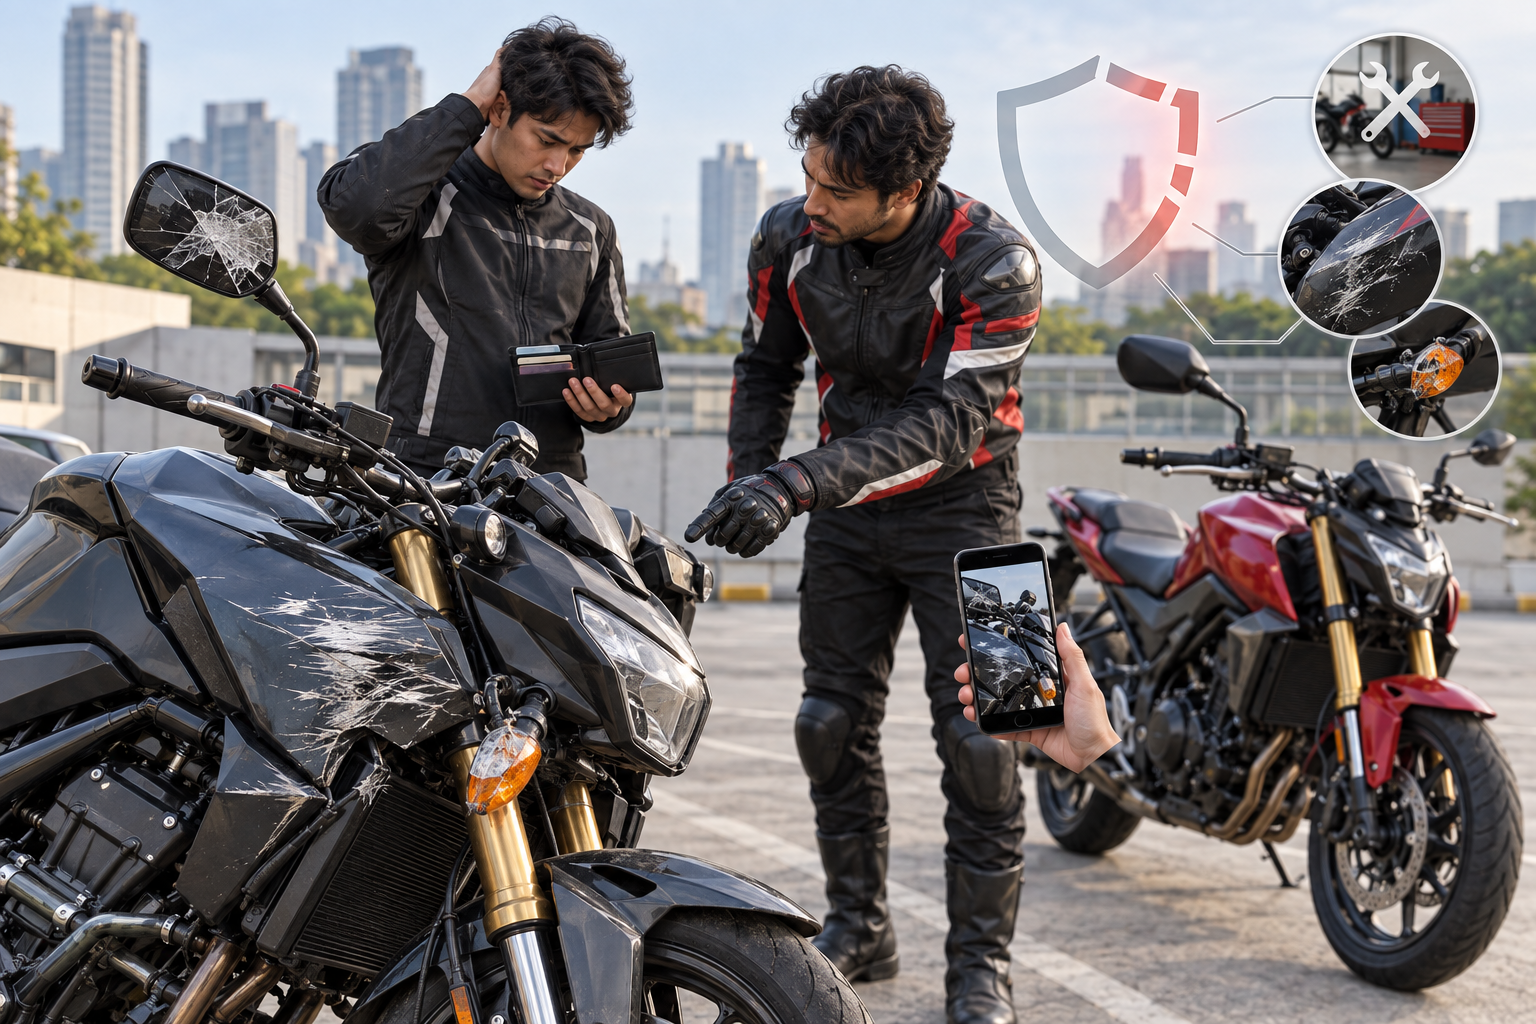
Take a hypothetical. Say the collision cracks the other rider’s side panel and indicator and the workshop quotes around ₹6,000. Your own bike needs a headlamp assembly and a front fender at roughly ₹9,000.
That first ₹6,000 goes through your insurer under third party liability, going by whatever the policy terms allow. The ₹9,000 is yours to find. And these figures shift a fair bit from one bike, city and workshop to the next, so read them as a rough illustration and nothing firmer.
Right After It Happens, What Should You Do?
How smoothly the claim moves later usually traces back to that first hour on the road.
- See whether anyone has been hurt. That comes ahead of everything else on this list.
- Swap names, phone numbers, registration numbers and policy details with the other rider.
- Get photos of both bikes, the damage and the spot itself, while everything is still where it landed.
- Lodge an FIR at the nearest police station if somebody is injured or the damage runs to a serious amount.
- Call your insurer inside the reporting window your policy allows, and that window is usually a short one.
A quiet cash settlement at the roadside looks convenient. It also leaves you with no record if the other rider returns later with a bigger number, so keep the paperwork even when the amount seems small.
What If You Have No Insurance at All?
Then the full bill sits with you, and you face a penalty on top of it. Riding without at least a valid liability policy is an offence under the Motor Vehicles Act, and the fine and possible imprisonment term have been revised more than once, so check the current position rather than relying on an old figure.
The money side is the heavier part. You would settle the other rider’s repairs directly, and if an injury claim reaches a tribunal, the award falls on you personally. That is why third party insurance for bike owners sits in the law as a floor rather than an optional extra.
Should You Move From Third Party to Comprehensive Cover?
That depends on what your bike is worth and what you can absorb after a bad day. Comprehensive adds own damage cover on top of the same mandatory liability, so your repair bill goes to the insurer instead of your wallet. It costs more each year, and it comes with conditions worth reading first.
- The insurer deducts depreciation on replaced parts before settling, and plastic and rubber parts depreciate faster than metal ones
- You pay a compulsory deductible on every own damage claim, which is the fixed share you cover yourself, plus any voluntary deductible you chose to reduce your premium
- Your settlement is limited by the Insured Declared Value, meaning your bike’s current market value after depreciation, not the price on your original invoice
For an older bike with a low Insured Declared Value, the annual premium can look large next to what a claim would realistically return. For a newer or costlier bike, the own damage half usually carries more weight. Comparing both options for two wheeler insurance online at renewal makes that trade visible, because premium and coverage sit next to each other on the same screen.
Terms and conditions apply. Please refer to the policy wording for full details before purchase.
The Short Version
Damaging someone else’s bike without comprehensive cover leaves you less exposed than most riders assume. Your mandatory liability cover already responds to the other rider’s repairs and to any injury claim brought against you, within the limits in your policy. What it will not do is fix your own bike, and that gap is the entire difference between the two policy types.
So the question at renewal isn’t whether you’re covered. It’s which half of the damage you’d rather carry. Pulling out your current policy schedule, checking the property damage limit on it and running a comprehensive quote for two wheeler insurance online will tell you where you stand in about ten minutes.
